
What Are the Risks of Selling a House As-Is?
Last updated: October 11, 2026
Max Cohen
Founder · FL Home Buyers
Quick Answer
Selling as-is can save you from taking on repairs before a sale, but it does not remove every obligation or risk. You still need to compare what you will receive after costs and debts, understand the buyer's inspection and cancellation rights, make required disclosures, and resolve closing requirements. A cash offer does not guarantee closing.
You can list a house as-is with an agent or consider a direct offer. As-is does not mean cash only or no inspection. The property's condition may limit financing or insurance options, so compare actual buyer terms rather than assuming every buyer can close.
Six Risks to Check Before Accepting an Offer
1. You may keep less than the offer price
Start with an estimated seller settlement statement. Include mortgage payoff, other debts or liens to be paid from the sale, seller charges, agreed credits, and applicable prorations. An offer price alone is not your net proceeds.
For the decision between selling as-is and repairing first, separately budget repairs and ownership costs paid before closing. Avoid counting the same expense or loan principal twice. Leave missing amounts unknown until you have an estimate or statement. Our as-is comparison guide shows how to label an incomplete comparison.
2. Inspections can still affect the sale
Read the inspection period, notice requirements, and cancellation terms before signing. The Florida Realtors/Florida Bar AS IS form gives the buyer inspection and termination rights. A buyer may ask for a price reduction or credit; a request alone does not change the agreed price. The signed agreement and applicable law determine the rights and deadlines. A repair discussion before an offer does not prevent a later dispute. See Florida Realtors' contract guidance.
3. The buyer may not be ready to fund the purchase
Confirm the buying entity, signer, source of funds, deposit terms, and any financing condition. Ask whether assignment is allowed and who remains responsible if the contract is assigned. A bank letter or escrow deposit does not guarantee closing. Verify the closing professional's identity and contact information independently before sending sensitive records or following payment instructions. Use our buyer and closing-contact checks when comparing offers.
4. As-is wording does not remove disclosure duties
For a Florida residential sale, sellers must disclose known facts that materially affect value, are not readily observable, and are not known to the buyer. An as-is contract does not remove that disclosure duty. Ask your own attorney how it applies to your facts. The Florida Bar explains the legal scope.
Florida also requires a residential seller's flood disclosure at or before the sales contract is executed. Review the questions about flooding, insurance claims, and assistance in section 689.302.
Federal lead disclosure requirements apply to most housing built before 1978, with exceptions. Complete the required disclosures and records before the buyer signs the contract; the rules also address an inspection opportunity. Follow the EPA instructions and our seller paperwork guide.
5. Title, debts, or signing authority can delay closing
Give the closing professional information about mortgages, liens, association balances, code or permit issues, and ownership questions early. Probate, divorce, bankruptcy, or a foreclosure deadline may also require your own attorney's involvement. Ask who must act, which documents are missing, and whether the proposed date is workable. A cash offer does not clear debts or establish authority to sell. If sale proceeds will not cover required payoffs and charges, resolve the shortfall before relying on a closing plan.
6. Waiting, upkeep, and move-out still need a plan
Budget payments and property expenses through the expected closing date, plus a possible delay. Check your contract's maintenance, utilities, access, and damage provisions. As-is does not automatically remove duties to maintain the property while under contract. Confirm the possession date, occupants, belongings, and any written agreement to stay after closing.
Ask the closing professional when funds can be released and how receipt will be confirmed. Signing alone does not mean sale funds have been released or received.
What to Ask Us or Any Buyer
Bring these questions to the offer discussion and put the answers in the written terms where appropriate:
- Who is obligated to buy, what funds are available, and can the contract be assigned?
- What property condition has been reviewed, and what inspections or other conditions remain?
- What allows either party to cancel, and what notices and deadlines apply?
- What could I receive after charges and debts, and which amounts are still unknown?
- What must happen before closing, payment, and possession can each occur?
Use your own attorney for contract interpretation or a dispute. This guide is general seller information. The Florida Realtors/Florida Bar form update illustrates inspection, maintenance, and possession provisions; your agreement may differ.
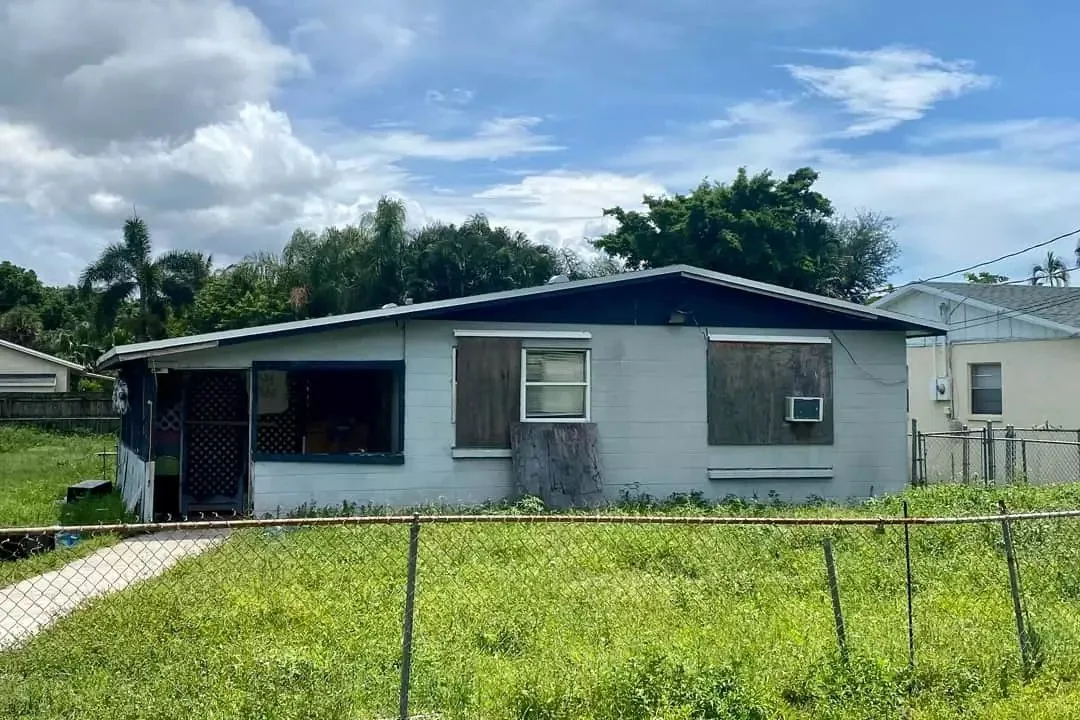
Published Florida Purchase History
These published entries identify purchase locations and years. They do not establish seller proceeds, closing speed, property condition, or a risk-free outcome. The linked pages use redacted street references.
To discuss an as-is offer, call (561) 258-9405 or request an offer online. Compare the written terms with your other options before deciding.